Now and Always, the Relevance of the Taylor Rule in Europe
Abstract
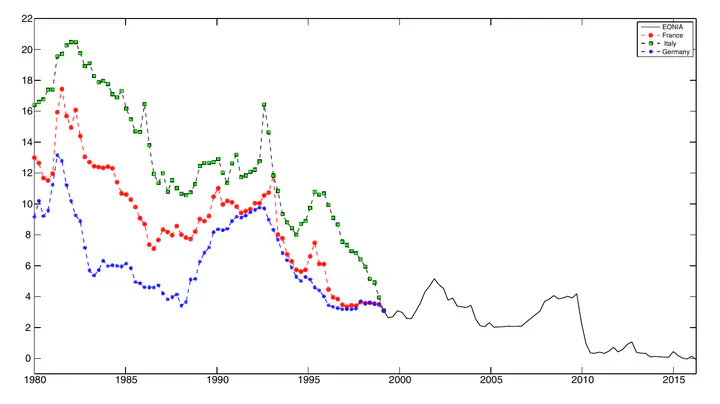
We find that, after the adoption of the euro, the European Central Bank has followed a forward-looking Taylor rule. This rule is such that nominal as well as real short-term interest rates increase in response to higher expected inflation or decline in output. Our findings show that the European Central Bank policy responses are of the same magnitude and sign as the ones prevailing in the pre-euro era for Germany, France, and Italy. We conclude that, before and after the euro, central banks in Europe have adopted a proactive stance towards controlling inflation.
Type
Publication
International Journal of Finance & Economics, 23(1), 41–46
Agustin Diaz Casanueva
Economist
I study how households make economic decisions about consumption, fertility, and labor supply in response to shocks and policy changes.